International cargo rarely arrives exactly as it left the warehouse. A wooden crate may face rain, vibration, rough handling, or sudden temperature changes. Even strong packaging cannot remove every transportation risk. Damage can affect products, delivery schedules, customer relationships, and cash flow. That is why cargo insurance deserves attention before shipment, not after a problem occurs. Small details matter.
Understanding how to insure international cargo against transit damage starts with identifying realistic risks. Consider the cargo’s value, route, transport methods, packaging, and storage points. A shipment moving through several ports may need different protection from cargo using one direct service. Professional brokers and experienced insurers can help compare coverage terms. However, their recommendations should be checked against the actual shipping contract and policy wording.
Reliable insurance decisions depend on clear records. Keep invoices, packing lists, photographs, inspection notes, and transport documents. These details can support a claim when damage appears at delivery. Review exclusions carefully, including inadequate packaging, ordinary wear, delay-related losses, and undisclosed cargo characteristics. Coverage limits and claim deadlines also deserve attention. A cheaper policy may provide less useful protection. That lesson is easy to miss. No policy removes every uncertainty, and insurance cannot replace careful packing or responsible carrier selection. Still, suitable transit coverage can create a practical financial safeguard when unexpected damage interrupts international trade. The strongest approach combines expert advice, accurate documentation, sound packaging, and realistic expectations. Mistakes can happen, even with experienced teams. Reviewing each shipment afterward can reveal weaknesses and improve future protection.
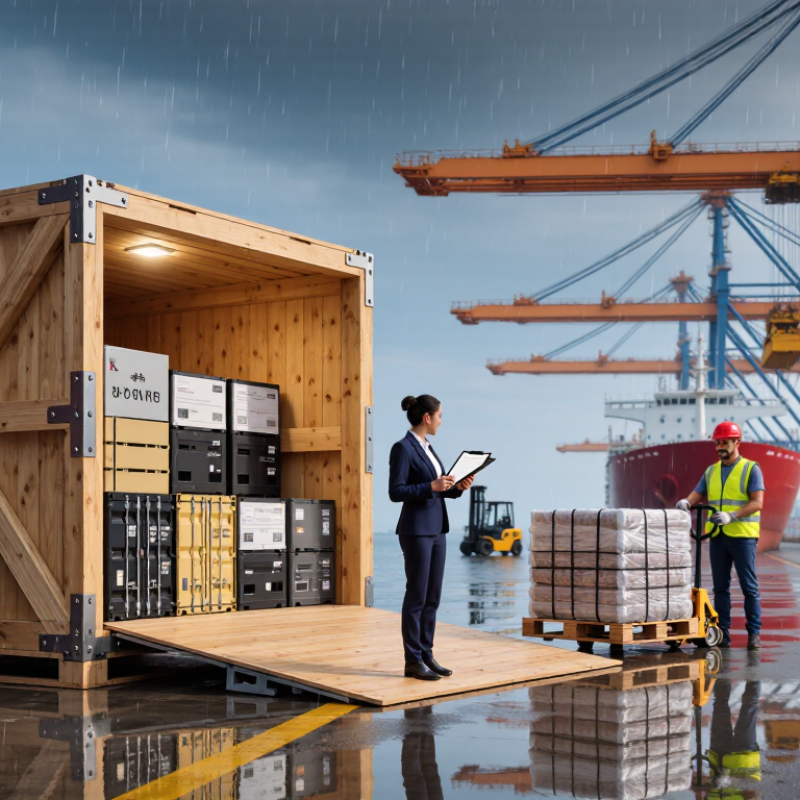
Define Transit Risk: 221 Containers Were Lost at Sea in 2023 (WSC)
Why Insure International Cargo Against Transit Damage?
Sea transport is safer than its reputation, but risk remains measurable. The World Shipping Council reported 221 containers lost at sea in 2023, including containers carried away during severe weather. That figure represented about 0.0003% of containers shipped, yet each loss can involve expensive goods, missing documents, and disrupted customer schedules.
Small probability. Serious consequences.
The Allianz Safety and Shipping Review 2024 recorded 26 total losses of large ships in 2023. A ship does not need to sink for cargo damage to occur. Heavy rolling can shift pallets, break packaging, or force seawater through damaged container walls. Temperature changes may also affect food, chemicals, electronics, and other sensitive cargo.
Insurance should match the actual transit risk, not an optimistic assumption. A cargo owner should review packing strength, container condition, weight distribution, moisture protection, and securing methods before loading. Photographs, inspection records, commercial invoices, and transport documents can support a clearer claim investigation. Coverage terms still require careful reading. Some policies limit protection for inadequate packing, delay, or natural deterioration.
In practice, claims often reveal preventable weaknesses. A carton may look strong but fail under repeated vibration. A sealed container may still contain hidden moisture. That is easy to miss. Independent risk assessments and documented loading procedures can reduce uncertainty, although they cannot remove it. Personally, treating the 221-container figure as “too small to matter” would be a costly mistake.
Measure Air-Cargo Exposure: 35% of Global Trade Value Moves by Air (IATA)
Why Insure International Cargo Against Transit Damage?
Air cargo carries about 35% of global trade value, according to the International Air Transport Association. That figure deserves attention. High-value electronics, medical equipment, precision parts, and urgent documents often travel by air because speed matters. Yet speed does not remove risk. Cargo may face loading impacts, vibration, moisture, temperature changes, or incorrect handling at transfer points.
The exposure is concentrated. A single damaged shipment can affect production schedules, customer commitments, and cash flow. Industry analyses from IATA also show that air freight represents less than 1% of global trade volume, but a much larger share by value. This imbalance explains why ordinary transport protection may be insufficient. A cargo policy can address physical loss or damage during covered transit, subject to its wording, exclusions, and declared value.
Documentation remains practical, not decorative. Shippers should record packaging condition, product sensitivity, route changes, and handover times. Photos help. So do temperature or shock records when the cargo requires them. The International Chamber of Commerce’s Incoterms guidance also shows why responsibility and insurance duties must be defined clearly between trading parties. A weak point remains: many teams insure the invoice value but overlook freight, duties, and recovery costs. That gap deserves review. Coverage should reflect the cargo’s real financial exposure, not only its price on paper.
Air freight represents about 35% of global trade value while carrying less than 1% of trade volume. This high-value concentration means that a relatively small number of damaged shipments can create significant financial exposure during international transit. Cargo insurance can help transfer eligible risks such as physical damage, loss, and handling-related incidents.
Match Insurance Scope to ICC Incoterms and Institute Cargo Clauses
Why Insure International Cargo Against Transit Damage?
International cargo faces more than obvious risks. A pallet may tip during crane handling, absorb moisture in a port warehouse, or arrive with crushed cartons. Incoterms determine when risk transfers between seller and buyer. They do not automatically provide complete insurance protection. The policy should match that transfer point, the goods, and the transport route.
Under CIP terms, the seller usually arranges broader cargo insurance, commonly aligned with Institute Cargo Clauses A or equivalent cover. Under CIF terms, the required protection is generally narrower, often aligned with Clause C. Clause C may cover major named events, but not every handling loss or water-related incident. Clause B offers wider protection, while Clause A is typically the broadest, subject to exclusions. These distinctions matter. A buyer expecting “full cover” may discover that poor packing, delay, or gradual deterioration is excluded.
Tips: Read the sales contract, Incoterm, insurance certificate, and policy exclusions together. Check whether the insured value includes freight, duties, and a reasonable margin. Confirm coverage from the warehouse to the final destination. Photograph damaged corners, wet labels, broken seals, and internal packaging immediately. Notify the insurer and carrier within stated deadlines. Small details decide claims.
A practical review should consider commodity sensitivity, container conditions, seasonal weather, and transshipment points. Fragile instruments need different protection from steel components. Refrigerated cargo needs temperature evidence. One imperfect assumption can leave a serious gap. Revisit coverage when routes, packaging, or delivery terms change.
Compare Premiums with Cargo Value, Damage Rates, and Delay Costs
Why Insure International Cargo Against Transit Damage?
Compare Premiums with Cargo Value, Damage Rates, and Delay Costs
A cargo premium should be measured against more than the invoice value. Consider a shipment worth $120,000. At a 0.35% premium, insurance costs about $420. That figure seems small beside a serious loss. However, the real decision depends on packaging, route history, handling points, and the cargo’s vulnerability.
Review your own damage records before choosing coverage. If similar shipments show a 2% damage rate, the expected loss may already exceed the premium. Use carrier reports, inspection records, and warehouse incident logs where available. A scratched machine may need replacement parts, specialist labor, and another inspection. The invoice rarely shows the complete cost.
Delay expenses can be even less visible. A missed production window may create storage charges, idle labor, urgent replacement freight, or contractual compensation. For a $120,000 shipment, three days of delay could cost more than physical repairs. Numbers can disappoint. Estimates are often too optimistic.
Compare the premium with the likely loss, not only the worst-case headline. Check deductibles, exclusions, valuation rules, and claim documentation requirements. A low premium may provide limited protection for fragile or time-sensitive goods. A higher premium may be reasonable when one damaged crate can interrupt an entire project. Still, insurance is not a substitute for stronger packaging, accurate labels, or careful loading. Small gaps matter.
Why Insure International Cargo Against Transit Damage? - Compare Premiums with Cargo Value, Damage Rates, and Delay Costs
Generalized international logistics planning benchmarks showing how insurance premiums compare with cargo value, physical-damage risk, and potential delay-related costs.
| Transport Mode |
Typical Cargo Profile |
Cargo Value per Shipment |
Indicative Premium Rate |
Estimated Premium |
Reported Damage Rate |
Expected Physical-Loss Exposure |
Average Delay |
Delay Cost per Day |
Delay-Cost Exposure |
| Ocean freight |
Consumer electronics in containerized cargo |
US$250,000 |
0.45% |
US$1,125 |
1.20% |
US$3,000 |
4.0 days |
US$1,800 |
US$7,200 |
| Ocean freight |
Industrial machinery and spare parts |
US$500,000 |
0.35% |
US$1,750 |
0.80% |
US$4,000 |
3.0 days |
US$2,200 |
US$6,600 |
| Air freight |
Temperature-sensitive pharmaceutical products |
US$300,000 |
0.75% |
US$2,250 |
0.50% |
US$1,500 |
1.0 day |
US$6,500 |
US$6,500 |
| Air freight |
Perishable food and high-value fresh products |
US$120,000 |
1.10% |
US$1,320 |
1.80% |
US$2,160 |
0.8 day |
US$4,200 |
US$3,360 |
| Cross-border rail |
Automotive components and engineered parts |
US$180,000 |
0.65% |
US$1,170 |
1.50% |
US$2,700 |
2.5 days |
US$1,400 |
US$3,500 |
| Cross-border road |
Apparel, footwear, and retail inventory |
US$80,000 |
0.90% |
US$720 |
2.40% |
US$1,920 |
1.5 days |
US$900 |
US$1,350 |
|
Calculation basis: Estimated premium = cargo value × indicative premium rate. Expected physical-loss exposure = cargo value × reported damage rate. Delay-cost exposure = average delay × estimated daily commercial impact. Premium rates and risk levels vary according to cargo type, packaging, route, season, security controls, deductible, and policy wording.
|
Interpretation: Even when the insurance premium is below 1% of cargo value, a single damaged shipment or delay can create a substantially larger financial exposure. The comparison is intended for budgeting and risk-screening purposes; actual coverage terms, exclusions, deductibles, and claim conditions should be reviewed before shipment.
Select Limits, Deductibles, and Claims Evidence for International Shipments
Why Insure International Cargo Against Transit Damage?
Selecting the limit is more than multiplying invoice value by freight cost. A shipment may also include duties, inspection fees, and reasonable recovery expenses. UNCTAD’s Review of Maritime Transport 2024 states that maritime shipping carries over 80% of global merchandise trade by volume. One damaged container can therefore create costly delays beyond the visible loss.
Choose a limit that reflects the cargo’s highest realistic exposure, not its average value. A deductible can reduce premium, but an excessive deductible may make smaller claims impractical. For fragile machinery, temperature-sensitive goods, or mixed cartons, review packing quality and handling points before setting either figure. The 2023 World Bank Logistics Performance Index highlights uneven tracking and tracing performance across international corridors. Better records matter.
Claims evidence should be gathered before opening the package. Keep commercial invoices, packing lists, transport documents, photos of seals, and delivery notes. Photograph crushed corners, water marks, broken pallets, and the surrounding packaging. Ask the carrier to record exceptions at delivery. Do not discard damaged materials too quickly. They may prove the cause.
Electronic timestamps help, but they are not perfect. A missing scan can weaken an otherwise valid file. That deserves honest review. In practice, clear evidence often matters as much as the policy limit. Insurance wording should also clarify concealed damage, survey requirements, notice periods, and salvage handling. Small wording differences can change the outcome.
FAQS
Cargo can tip during crane handling, absorb moisture, or arrive with crushed cartons.
Match coverage with the agreed risk-transfer point and the full transport route.
No. Basic clauses usually cover only listed major events.
Poor packing, delay, gradual deterioration, and some handling losses may be excluded.
Compare the premium with likely physical loss, repair costs, and delay expenses.
Consider freight, duties, inspections, recovery work, specialist labor, and replacement transport.
Set the limit against the highest realistic exposure, not the average shipment value.
Keep invoices, packing lists, transport documents, delivery notes, and seal photographs.
Review commodity sensitivity, packaging quality, container conditions, weather, and transfer points.
Conclusion
International cargo faces a range of transit risks, including rough seas, handling accidents, theft, weather events, and delays. In 2023, 221 containers were lost at sea, showing why even well-managed shipments need financial protection. Air freight also deserves attention because approximately 35% of global trade value moves by air, where high-value goods can be exposed to damage, loss, and disruption. Understanding how to insure international cargo against transit damage begins with assessing the route, transport method, cargo characteristics, and likely financial impact.
Coverage should match the agreed delivery responsibilities under applicable Incoterms and the selected Institute Cargo Clauses. Businesses should compare premiums with cargo value, historical damage rates, replacement expenses, and delay-related costs rather than choosing solely by price. Appropriate policy limits and deductibles can balance protection and affordability. Clear commercial invoices, packing lists, transport documents, inspection reports, photographs, and timely notifications are also essential for supporting a claim and resolving a loss efficiently.
 Changi Logistics